Why Some Vermont Homeowners Might Consider an Adjustable Rate Mortgage Instead of a Fixed Rate Mortgage
When purchasing a home in Vermont, one of the biggest financial decisions you’ll face is choosing between a fixed rate mortgage and a variable rate mortgage (also known as an adjustable rate mortgage, or ARM). While fixed rate mortgages offer stability, variable rate mortgages can offer lower initial costs — but with more uncertainty over time.
A variable rate mortgage is a home loan where the interest rate can change periodically, based on market conditions. These loans typically start with a lower interest rate for an initial period — commonly 5, 7, or 10 years — and then adjust annually based on a benchmark rate such as the Secured Overnight Financing Rate (SOFR) or a U.S. Treasury index.
For example, a 5/1 ARM has a fixed rate for the first five years, then adjusts once per year after that.
By contrast, a fixed rate mortgage locks in a single interest rate for the entire life of the loan — usually 15, 20, or 30 years. The monthly principal and interest payments stay the same, regardless of market changes.
1. Lower Initial Interest Rate:
ARMs typically start with a lower rate than fixed mortgages, resulting in lower monthly payments for the initial term.
2. Short-Term Affordability:
If you plan to sell or refinance before the adjustment period begins, you may benefit from the lower initial rate without facing future increases.
3. Potential for Lower Long-Term Costs:
If interest rates stay the same or decrease after the initial fixed period, your total loan cost may be lower than with a fixed rate mortgage.
1. Uncertainty and Rate Increases:
After the initial period, your interest rate could rise significantly, leading to much higher monthly payments.
2. Budgeting Challenges:
The unpredictability of future payments can make long-term financial planning more difficult.
3. Payment Shock:
If rates rise sharply, homeowners may experience a sudden and unaffordable jump in monthly mortgage costs.
• Short-Term Homeownership Plans:
If you plan to sell your home within 5–10 years, you may benefit from the lower initial rate without being affected by future adjustments.
• Strong Income Growth Potential:
If you expect your income to increase significantly in the near future, you may be better equipped to handle potential rate hikes later on.
• Falling or Stable Interest Rate Environment:
If interest rates are expected to decline or remain stable, an ARM could remain affordable even after it begins adjusting.
• Long-Term Homeownership:
If you plan to stay in your home for more than 10 years, a fixed rate may offer more financial security.
• Tight Monthly Budget:
If your finances are stretched thin, even small rate increases could lead to payment stress or default risk.
• Rising Interest Rate Environment:
If rates are expected to climb, an ARM can become significantly more expensive over time.
At Peet Law Group, we understand that every Vermont homebuyer has unique financial goals. While variable rate mortgages offer potential savings, they also come with risks that require careful consideration. Before committing to any loan product, it’s essential to work with both a knowledgeable lender and a Vermont real estate attorney who can help you understand your obligations — and protect your interests throughout the process.
Learn what a real estate attorney costs in Vermont for a home purchase, sale or refinance, including current Peet Law Group flat-fee pricing.
Selling a Vermont home with a mortgage? Learn how your mortgage is paid off at closing, how payoff statements and discharges work, and what happens if an old mortgage appears in the land records.
Learn when a Vermont seller may cancel a home sale and what can happen if a seller refuses to close.
Learn what a low Vermont home appraisal means for buyers and sellers, including financing, price negotiations, contingencies and closing options.
Peet Law Group was named Best Vermont Law Firm in the 2026 Seven Daysies Awards for the fourth consecutive year. Thank you to our clients and industry partners.
Learn what closing costs Vermont home sellers typically pay, including real estate commissions, attorney fees, mortgage payoffs, taxes, and non-resident withholding.
Learn what to review before closing on a Vermont condo purchase, including resale certificates, special assessments, association finances, insurance, rules, and more.
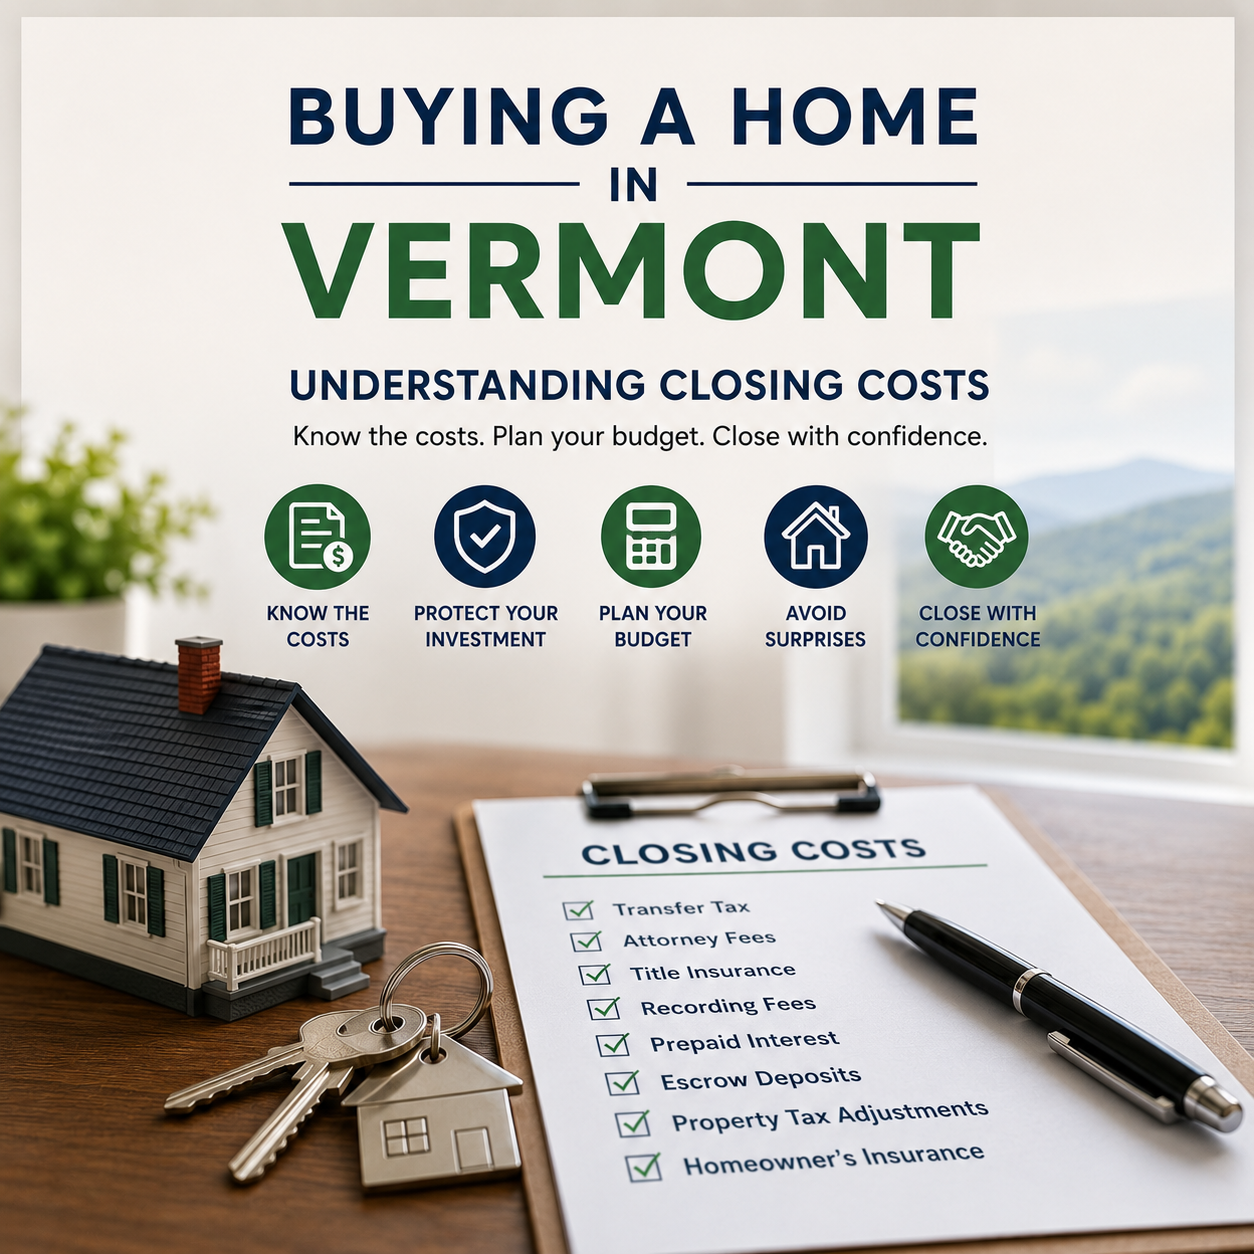
Learn what closing costs Vermont home buyers pay, including transfer tax, title insurance, attorney fees, lender costs, escrow deposits, and more.
Why Every Married Vermont Homeowner Should Understand Tenancy by the Entirety
Buying or Selling a Home in Vermont? Here's What Happens After the Contract Is Signed